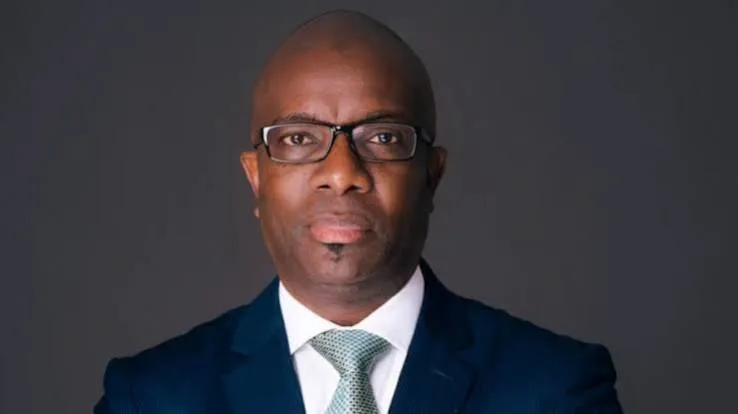
Standfirst: Étienne-Claude Mabunda takes charge of Ecobank RDC as the bank pursues a sharp expansion in assets, revenue and distribution. His experience in Congolese corporate finance—and Ecobank’s growing engagement with the mining supply chain—could make the sector an important part of that strategy.
Étienne-Claude Mabunda’s appointment as chief executive of Ecobank RDC gives the former Rawbank executive responsibility for one of the more ambitious expansion plans in Congolese banking.
Ecobank RDC’s previously published targets call for its total assets to exceed $1 billion in 2026, up from approximately $590 million at the end of 2025. The bank has also targeted net banking income above $100 million, pre-tax profit of $30 million and a cost-to-income ratio below 60%.
Those objectives pre-date Mabunda’s appointment on September 10. They should therefore be understood as the institutional plan he inherits, rather than promises made personally by the new chief executive. Their scale nevertheless defines his immediate mandate: expand the bank’s balance sheet, attract more deposits and build a larger portfolio of commercially viable loans.
Ecobank also plans to increase its network to 18 branches and 3,500 active agents, before reaching 30 branches, 10,000 agents and three million retail customers by 2030. It had more than 200,000 customers when the expansion was described, illustrating the distance between its existing position and its longer-term ambition.
Mining offers scale, but not without concentration risk
Mining is an obvious commercial opportunity. The sector creates demand not only for corporate loans, but also for payments, foreign-exchange services, guarantees, equipment finance, payroll management and working capital for contractors.
Ecobank’s presence in Kolwezi and Likasi places it close to the mining and service economies of Lualaba and Haut-Katanga. Its participation in DRC Mining Week also indicates a deliberate effort to reach operators, investors and suppliers. Event sponsorship alone does not establish a mining-finance portfolio, but it places the bank inside the commercial network from which such business could emerge.
Mabunda brings relevant experience. During his more than 20 years at Rawbank, he worked across retail, corporate and institutional banking before becoming commercial director. In January 2025, while he held that position, Rawbank arranged a $10 million negotiable-debt issuance for a Katanga mining operator. The transaction included a corporate guarantee that the bank described as a first for the Congolese market.
That experience matters because Ecobank’s billion-dollar balance-sheet target cannot be achieved through branch expansion alone. The bank will need larger corporate relationships and stronger transaction volumes without allowing credit growth to weaken asset quality.
Mining can provide both. Large operators generate considerable payment flows, while their networks of contractors create demand for smaller facilities. But lending heavily to one industry also exposes a bank to commodity cycles, operational disruptions and changes in mining regulation.
A larger platform for supplier finance
Ecobank RDC already has a mechanism that could help it expand below the level of major mining companies. In May 2026, British International Investment and the bank announced a $30 million risk-sharing facility intended to increase lending to Congolese SMEs. Target sectors include industry, infrastructure, renewable energy and other areas that overlap with the needs of the mining supply chain. BII describes the partnership as a way to expand sustainable SME financing in the DRC.
Risk sharing is particularly relevant for contractors that possess commercial opportunities but lack the collateral, financial history or balance-sheet strength normally required by banks. It can allow Ecobank to finance more businesses while limiting its exposure to individual defaults.
The bank’s Ellever programme adds another route into the sector. It combines finance, training, mentoring and market access for women-led businesses, including companies operating in mining services, logistics and equipment supply. According to Mining & Business, the programme has supported more than 500 women entrepreneurs and provided over $20 million across its participating sectors, with a stated lending target of $100 million by 2030. The available figures do not disclose how much has gone specifically to mining businesses.
Mabunda’s opportunity is therefore wider than lending directly to mine operators. Ecobank could position itself across the financial chain connecting mines with transporters, equipment companies, maintenance providers and other Congolese suppliers.
The evidence of success will not be the number of mining events the bank attends. It will be whether Ecobank discloses new transactions, grows its contractor-finance portfolio and converts its regional network into measurable business across the DRC mining economy.
Can Ecobank Turn Its African Mining-Finance Model Into Growth in the DRC?
Standfirst: Ecobank has demonstrated that African banks can finance processing plants, mining equipment and cross-border industrial transactions. Applying that model in the DRC would require more than capital: the bank would need to manage contractor risk, commodity exposure and the operational demands of the Copperbelt.
Ecobank does not need to invent a mining-finance model for the Democratic Republic of Congo. Parts of that model already operate elsewhere in its African network.
In February 2026, Ecobank Sierra Leone announced two mining transactions worth a combined $65 million. A $40 million facility for Sierra Rutile was structured to finance the acquisition and relocation of a mineral-sands processing plant from Kenya to Sierra Leone. A further $25 million package for Meya Mining covered diamond-processing equipment, mining vehicles and supporting infrastructure as the company moved towards commercial production.
The transactions were led by Ecobank Sierra Leone with support from Ecobank Ghana. They combined project requirements, equipment acquisition and cross-border execution—capabilities that are directly relevant to mining markets where imported machinery and regional supply chains remain central to mine development.
This does not mean that Ecobank RDC already possesses an equivalent mining portfolio. The Sierra Leone transactions demonstrate group capability, not local deployment. The strategic question is whether the bank can reproduce those capabilities in a larger and more competitive Congolese market.
From mine finance to the operating supply chain
The most realistic opening may not be financing an entire copper or cobalt project. Large mines generally rely on international lenders, shareholder funding, commodity traders and syndicated facilities capable of providing longer tenors and larger amounts than a local subsidiary can carry alone.
Ecobank can compete around those projects.
Its published trade-finance offering includes import and export facilities, letters of credit, customs and performance guarantees, trade loans, bill discounting and structured commodity finance. The bank says it has experience in metals finance and can distribute larger transactions among financial institutions through club or syndicated structures.
These services correspond to practical mining requirements. Equipment distributors may need import finance. Contractors bidding for mine work require performance guarantees. Producers need payment and foreign-exchange services. Exporters require documentation, collections and risk mitigation across several jurisdictions.
Ecobank’s operations across 36 African markets offer another advantage. The DRC mining industry is connected to Zambia, South Africa, Tanzania, Mozambique and Angola through equipment procurement, engineering services, processing inputs and export corridors. A bank capable of managing transactions across those markets can compete on network reach rather than balance-sheet size alone.
The bank’s partnership with XTransfer also expands its Africa–China payment proposition. That connection is commercially relevant because Chinese companies occupy important positions in Congolese mining, while numerous Congolese suppliers import machinery, components and industrial goods from China. The platform is intended to reduce the cost and complexity of cross-border payments for SMEs, although its actual adoption in the DRC mining supply chain has not been disclosed. The Ecobank–XTransfer arrangement targets SME trade between Africa and China.
The contractor-finance gap
A second opportunity lies between the mining companies and their local suppliers.
The DRC is enforcing requirements intended to direct more subcontracting business towards eligible Congolese-owned companies. Legal access to contracts, however, does not automatically provide the capital needed to execute them. Contractors may need vehicles, machinery, inventory, insurance, payroll funding and working capital before a mining customer settles an invoice.
Ecobank’s Ellever programme already addresses part of this market by targeting women-led businesses in mining services, logistics and equipment supply. Its $30 million risk-sharing partnership with BII could provide a broader foundation for SME lending.
The stronger model would connect finance to verified contracts. Instead of relying primarily on conventional collateral, the bank could assess purchase orders, approved invoices and payment histories with established mining operators. That approach would still require disciplined credit controls, particularly where contractors depend heavily on a single customer.
There are also limits. Commodity-price volatility can weaken both mine operators and suppliers. Congolese businesses often lack audited accounts, and specialist mining equipment may be difficult to recover or resell. Dollar liquidity, regulatory compliance and environmental and social standards can further restrict financing.
Ecobank nevertheless has the relevant components: a pan-African network, structured trade products, development-finance risk sharing and evidence that other subsidiaries can execute mining transactions. Under new chief executive Étienne-Claude Mabunda, the question is whether those separate capabilities will be assembled into a visible DRC mining-finance strategy.
The clearest proof would be a portfolio of disclosed transactions: equipment facilities, contractor working-capital lines, payment solutions and larger syndicated deals tied to Congolese mining operations. Until then, Ecobank’s mining opportunity in the DRC remains credible—but more prospective than demonstrated.